

Budget Calendar

- 189.00 Reviews
- 4.8
- Downloads
- 10,000+
Our take on Budget Calendar from Appgk
Managing money often becomes difficult at the exact moment life gets busy. Bills arrive on different days, paychecks follow their own schedule, and a monthly total can hide the uncomfortable gap between having enough money overall and having enough money today. Budget Calendar takes a more practical view: it puts budgeting on a calendar so I can see when money is expected to arrive and when it is likely to leave.
I reviewed this finance app from the perspective of someone trying to plan ordinary household spending rather than build a complicated financial model. Developed by MiShell Software Systems, it is a paid app priced at $4.95, with an Everyone age rating. Its appeal is not flashy presentation or a huge collection of financial tools. The appeal is the simple handoff between a date and a financial decision: enter an income or expense, place it where it belongs, and look ahead before committing to another purchase.
That approach makes it especially interesting for people who think better in terms of days than categories. If you regularly ask yourself whether a bill will arrive before payday, whether a subscription has been forgotten, or whether a weekend purchase will make the next week uncomfortable, this format can be more useful than a conventional expense list.
From a vague money worry to a dated plan
The starting condition for many users is not a lack of financial information. It is a lack of timing. A bank balance may look healthy, but that balance could already be spoken for by rent, utilities, transport, school costs, or an annual renewal. A standard budgeting app usually asks me to think in monthly categories. Budget Calendar asks me to think about the sequence of events.
Best Parts of Budget Calendar
Things to Keep in Mind About Budget Calendar
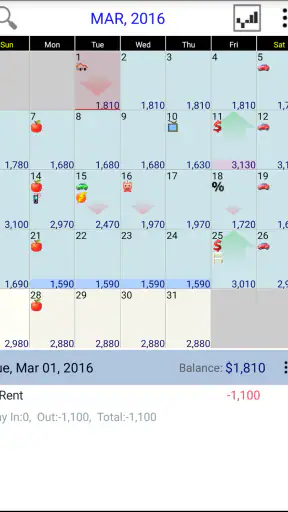
That difference matters when income is irregular, when bills are scattered across the month, or when two people share responsibility for expenses. Instead of treating the month as one large container, I can inspect the days around a payment and see what the balance is expected to handle next. The calendar view turns an abstract budget into a schedule, which is easier to discuss with another person and easier to check before making a decision.
My recommended first step is to enter the items that are hardest to move: regular income, housing costs, utilities, loan payments, insurance, and other known commitments. I would not begin by recording every coffee or snack. The first goal is to create a dependable skeleton of the month. Once that structure is visible, smaller spending becomes easier to judge because it has context.
News and Features Related to Budget Calendar

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
News
Moovit Review: A More Reliable Way to Navigate Everyday Transit
News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
This is one of the app’s less obvious strengths. A calendar budget does not need to be perfectly detailed to be useful. It can first answer a narrower question: which dates are already financially crowded? That answer is often more valuable than a beautifully categorized record that I never consult.
Building the calendar without overwhelming yourself
I would set up the app in passes. The first pass should contain predictable money movements. The second can add flexible items such as groceries, fuel, entertainment, or planned purchases. The third is where I would correct the plan after comparing it with real life. This staged workflow prevents the common mistake of abandoning a budget because entering everything feels like a project.
Don't want to read the full review?
When an expense repeats, I would treat the recurrence as a convenience rather than a reason to stop checking. A recurring charge may change, be paused, or move because of a weekend or holiday. The calendar is most useful when I review the upcoming period and adjust anything that no longer matches reality. The practical habit is not “set it once and forget it”; it is “keep the next few weeks believable.”
I also found that the date itself deserves attention. Recording an expense on the day I usually notice it is not always the same as recording it on the day the money is likely to leave. For cash-flow planning, the latter is usually more helpful. That distinction can reveal why a month feels tight even when the total income and total expenses appear reasonable.
Screenshots
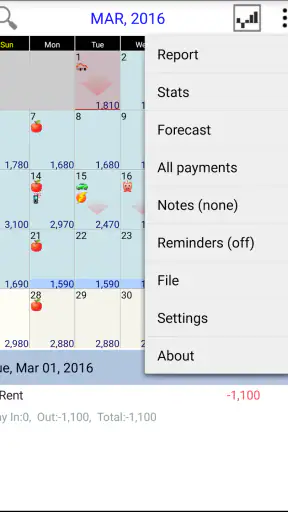
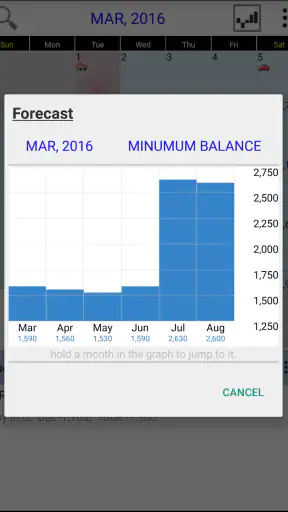
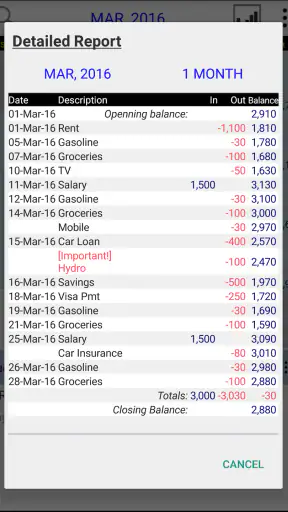
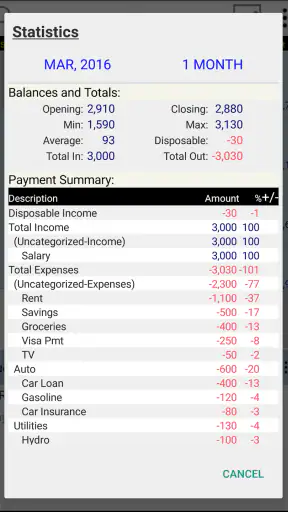
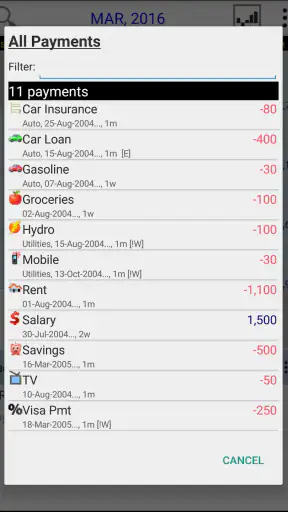
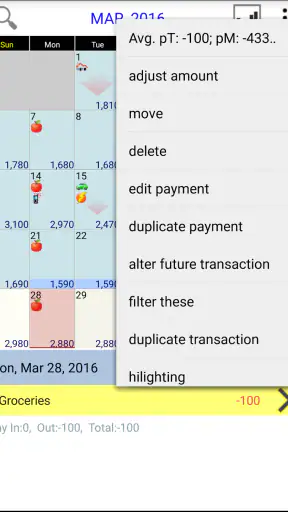
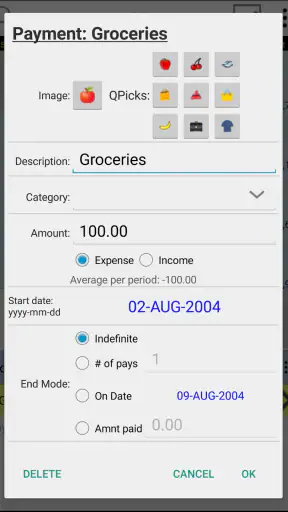
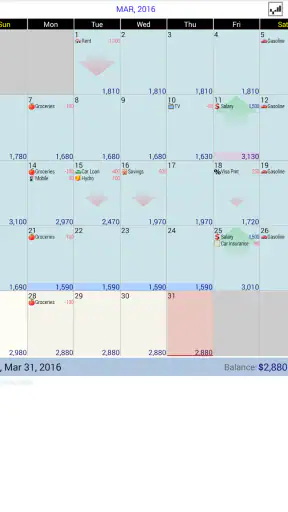
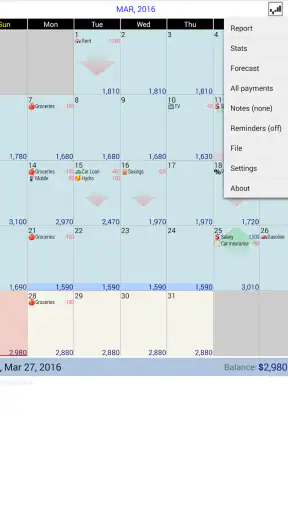
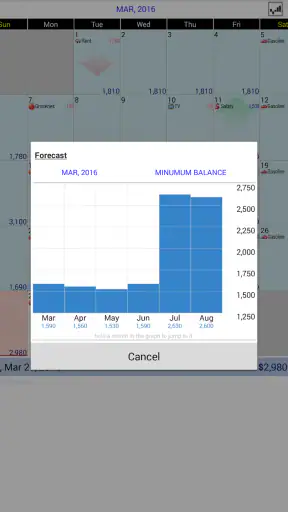
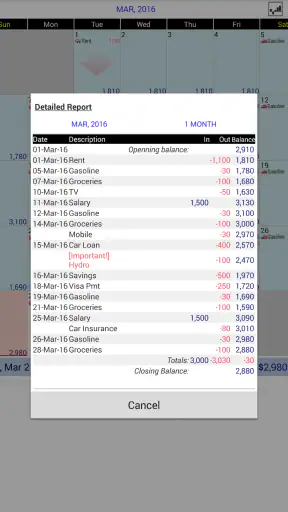
For shared finances, I would use a simple naming convention inside entries, separating household commitments from personal spending in a way that remains readable on the calendar. This is not the same as creating a full shared account system, but it makes a review conversation more concrete. Instead of saying “we spent too much,” I can point to the dates that created pressure and decide which future item should move.
Following one ordinary month from input to outcome
Imagine a user is paid near the beginning of the month. Rent is due shortly afterward, utilities arrive later, and a larger grocery trip usually happens around the middle. The user also has a streaming renewal and a planned family outing. In a typical category budget, all of these may sit under separate headings. In this app, the first useful question is whether the order of those events leaves enough room between them.
I would enter the income first, then place the fixed commitments on their expected dates. Next, I would add the grocery trip and outing as planned expenses rather than treating them as surprises. Looking across the calendar, I can decide whether the outing belongs before the utility payment, after it, or in the following period. The result is not merely a spending total; it is a decision made before the money is gone.
This workflow is particularly helpful for a person who receives money more than once during a month. The calendar can show which expenses belong to the first payment and which should wait for the next one. That is a more realistic way to plan than dividing all monthly income into broad percentages, especially when the dates of income and bills do not line up neatly.
A useful habit is to review the calendar before shopping for a large nonessential item. I would look at the next several financial events, not just the current balance. If the purchase falls between two heavy commitments, postponing it may be sensible even if the present day looks comfortable. Conversely, if the upcoming stretch is light, the calendar can provide a clearer basis for saying yes without relying on guesswork.
The handoff from planning to daily use is where many budgeting tools lose people. A plan made at the start of the month becomes stale after one unexpected expense. With Budget Calendar, I would update the relevant entry as soon as an amount changes, then inspect the affected dates again. The point is not to preserve the original plan. The point is to keep the forward view useful.
Turning the calendar into a conversation
Another practical handoff is between the person who enters information and the person who makes spending decisions. A category report can require explanation, while a dated calendar is easier to understand at a glance. If one partner handles bill payments and another handles groceries, both can discuss the same sequence: money arrives, fixed costs leave, flexible spending fits into the remaining space.
This also works for personal finances when responsibilities change during the month. Before traveling, moving, or starting a new payment arrangement, I would use the calendar to identify which commitments need attention before the change. It is a planning aid, not a replacement for checking the actual account, but it gives the conversation a shared structure.
There is a trade-off here. A calendar is excellent for timing, but it may be less satisfying for someone who wants deep merchant analysis, automatic classification, investment tracking, or a detailed net-worth picture. Those users may prefer a full personal-finance platform or a spreadsheet that can be customized extensively. Budget Calendar is narrower, and that narrowness is part of both its usefulness and its limitation.
What the result looks like after consistent use
After the calendar has been maintained for a while, the main result is better anticipation. I can see crowded periods earlier, identify expenses that repeatedly cause trouble, and distinguish a genuinely expensive month from one that is merely badly timed. That insight can lead to practical changes, such as moving a discretionary purchase, building a cushion before a known renewal, or spreading a planned cost across several pay periods.
The app’s store rating is 4.8 from 481 ratings, and its install base is over 10K. Those figures suggest that the focused calendar idea resonates with a meaningful group of users, although popularity alone does not decide whether the workflow suits me. The more important question is whether I naturally check dates when making money decisions. If I do, the format feels direct. If I prefer charts and category summaries, it may feel too limited.
Budget Calendar has been available since May 17, 2013, and the current version is 1.69. That long presence makes it feel like a focused utility rather than a trend-driven finance product. I would still approach it with the expectations appropriate to a compact budgeting tool: its value comes from the method and the routine, not from a promise to automate every part of financial management.
The price also changes how I judge it. At $4.95, I would expect to use it repeatedly rather than install it for a one-time experiment. For someone who has tried free budgeting tools but never kept them because category screens felt disconnected from real payment dates, the one-time cost can be reasonable. For someone who only needs to record a few monthly expenses, a notes app or simple spreadsheet may be enough.
Where the workflow becomes uncomfortable
The biggest weakness is the need for active maintenance. A calendar plan is only as trustworthy as the entries behind it. If I forget a bill, leave an old amount unchanged, or fail to account for an unexpected purchase, the future view can become misleading. The app helps organize information; it cannot know whether my real-world assumptions are still correct.
That limitation is more serious for people who want automatic financial awareness. If my ideal experience is for transactions to appear without manual input, this is probably not the right choice. The calendar method rewards users who are willing to enter, review, and correct their plans. It is less suitable for someone who wants a passive dashboard that simply reads the account and explains what happened.
There is also a mental adjustment when moving from a traditional budget. Category-based tools answer questions such as “how much did I spend on food?” A calendar answers “what will happen around this date?” Those are not interchangeable. If category control is my main goal, I may need another tool alongside this one, because the calendar view prioritizes timing over detailed spending analysis.
Another friction point appears when amounts are highly unpredictable. Freelancers, commission-based workers, or households with frequent variable costs can still use the app, but their plan will require more frequent revision. In that situation, I would enter conservative income expectations and avoid treating projected surplus as available money until it actually arrives. The calendar can support uncertainty, but it should not disguise it.
I would also avoid using it as the sole record for important financial decisions. Before paying a bill or transferring money, I would check the real bank balance and the biller’s information. The app is best viewed as a forward-planning layer. It helps me decide what should be possible; it is not a substitute for confirming what has actually cleared.
Who should make the switch, and who should pass
I would recommend this finance app to someone who gets paid on a predictable or semi-predictable schedule, has several bills spread across the month, and wants a quick visual answer about upcoming pressure. It is also a good fit for people who dislike complex budgeting language. The calendar gives a concrete place to start, and the workflow can remain simple even when the household’s finances are not.
It is especially useful for a short planning ritual: review the next few weeks, add any known commitment, compare the timing of income and expenses, and decide what can safely happen next. That routine is more valuable than entering a large historical archive and never looking at it again. I would begin with the next pay cycle, then expand once the habit feels natural.
I would skip it if I need automatic transaction imports, advanced reports, investment tools, or a highly collaborative household platform. I would also choose a spreadsheet if I wanted to design custom formulas and reports, or a broader finance service if I wanted one place for accounts, categories, goals, and long-term analysis. The calendar approach is not a universal replacement; it is a focused answer to cash-flow timing.
Device compatibility is another practical checkpoint. The listed minimum operating system is 7.0, so users should make sure their Android device meets that requirement before paying. The Everyone rating makes it suitable from an age-classification perspective for a broad audience, but the more important personal question is whether the user is comfortable taking responsibility for entering and reviewing financial information.
My final assessment after using the full workflow
Budget Calendar succeeds because it turns a vague feeling of financial tightness into a sequence I can inspect. I start with income and fixed commitments, add flexible plans, review the handoffs between dates, and then adjust the next decision based on what is actually coming. That is a modest idea, but it addresses a real problem that category totals often leave untouched.
Its best use is not as a complete financial command center. It is as a clear planning surface for people who need to know when money will be available and when it will be committed. The app asks for manual attention, and that can feel like work. In return, it gives me a more grounded way to think about the month than a single balance or a collection of disconnected categories.
My honest recommendation is therefore conditional but positive. If dates, pay cycles, and bill timing are the source of most of your budgeting stress, the focused design is worth considering at its $4.95 price. If you want automation or deep financial analysis, choose a broader alternative instead. For the right user, this compact tool makes the most important budgeting question much easier to answer: not only “can I afford it,” but “can I afford it when it happens?”
Budget Calendar FAQ
What is Budget Calendar and how does it work?
Budget Calendar is a personal finance app that organizes your income, bills, subscriptions, and everyday expenses on a calendar-style interface. After entering your expected transactions, you can see when money is coming in and going out, helping you plan ahead. This visual approach makes it easier to identify busy payment periods and avoid unpleasant surprises.
Can Budget Calendar help me track recurring bills and subscriptions?
Yes. Budget Calendar is designed to make recurring financial commitments easier to manage. You can add regular bills, rent, loan payments, subscriptions, and other scheduled expenses, then review them by date. This is particularly useful for spotting forgotten subscriptions or several payments falling within the same week. You should still verify amounts manually when a provider changes its pricing.
Is Budget Calendar suitable for creating a monthly budget?
The app can be useful for monthly planning because it lets you compare expected income with scheduled expenses across the calendar. You can estimate how much money should remain after bills and identify periods when spending needs to be reduced. However, it works best as a planning and cash-flow tool, so users seeking advanced investment analysis or detailed accounting may need another application as well.
Does Budget Calendar connect directly to my bank account?
Whether automatic bank synchronization is available depends on the version, platform, and services supported in your region. Many users may need to enter transactions manually or update them themselves rather than relying entirely on live account data. Before downloading, review the app’s current permissions, synchronization options, supported financial institutions, and privacy policy if automatic connections are important to you.
Is Budget Calendar safe to use for personal financial information?
Budget Calendar may contain sensitive information such as income details, bill amounts, and spending plans, so privacy should be considered before adding data. Use a strong device passcode, enable any available app security features, and download only from an official store. Also read the developer’s privacy policy to understand what information is stored, collected, or shared.











